A life interest creates a proprietary life tenancy, giving broader legal rights including possible income and, in some states, land tax exposure. A right to reside is a personal licence to occupy only, with no power to rent, sell, or mortgage. Choose a life interest when the occupant needs financial flexibility; choose a right to reside when preserving capital for remainder beneficiaries matters most, and always check state land tax and social security consequences before finalising either clause.
TL;DR:
- A life interest grants proprietary rights, allowing the occupant to rent, mortgage, and be responsible for land tax if applicable, unlike a right to reside, which is purely personal.
- Land tax liability for a life interest depends on the property not being the principal residence, potentially shifting costs to the remainder beneficiaries.
- Using clear, precise legal language in wills minimizes disputes, especially when specifying termination events and whether the interest is portable to other properties.
- A right to reside is generally unregistrable, income-free, and shields the occupant from creditors, making it more suitable for preserving capital for remainder beneficiaries.
- State-specific land tax rules, income tax consequences, and Centrelink impacts should be carefully considered before establishing either interest type.
Table of Contents
- Life interest vs right to reside: what a life estate actually gives you
- What a right to reside actually allows
- Which one actually protects your beneficiaries?
- Drafting language that avoids a family provision claim
- Tax and Centrelink effects you can’t ignore
- Ending the interest and handling disputes
- How to decide which option suits your estate plan
- A practitioner’s view from Simons George Legal
- Funding Your Legal Matter — No Win, No Fee
- Sources
- FAQ
Life interest vs right to reside: what a life estate actually gives you
A life interest is a proprietary interest in land, not a favour written into a will. It can be registered on title, and that registration is what separates it from a simple promise to let someone stay put.
Because it is a genuine estate in the property, a life tenant typically gets far more than a place to sleep:
- The right to occupy the property personally
- The right to rent it out and keep the income
- In some cases, the power to mortgage or even sell the interest, subject to the remainder beneficiaries’ rights
- Responsibility for rates, insurance, and maintenance
- Possible liability for land tax if the property is not the life tenant’s principal place of residence
The Mondaq analysis of life estates and rights to reside confirms this owner-like treatment can extend to land tax in some states. When the life tenant dies or the estate ends by some other trigger written into the will, the property reverts automatically to the remaindermen named in the will.
What a right to reside actually allows
A right to reside is a personal licence, not an estate in land. It gives someone permission to live in a property, full stop. There is no proprietary interest to register, and in most Australian jurisdictions it simply cannot be registered on title.
That narrower scope shapes everything else about how it works:
- Occupation only. No renting, no mortgaging, no selling the interest
- Often conditional. Many wills end the right if the occupant remarries, repartners, or moves permanently into aged care
- Outgoings are usually set out separately. The will should specify who pays rates, insurance, and repairs
- The estate retains more control over the asset, since nothing is handed over except occupation
Because it carries no ownership rights, a right to reside preserves the property’s capital value for remainder beneficiaries far more cleanly than a life interest does. It also ends more simply. Once the occupant vacates permanently or a specified trigger event happens, the licence terminates and the property becomes available for distribution.
Which one actually protects your beneficiaries?
The real divide comes down to proprietary rights versus a personal licence. A life interest is registerable, gives the life tenant income and transaction rights, and can expose the property to the life tenant’s creditors. A right to reside is unregisterable, income-free for the occupant beyond living there, and largely shielded from that occupant’s creditors because there is no proprietary interest for creditors to reach.
- Registration: life interest often can be noted on title; right to reside usually cannot
- Financial upside: life tenant may rent or, in some structures, sell subject to remainder rights; occupant under a right to reside gets neither
- Cost liability: rates, insurance, and land tax responsibilities need to be spelled out for either arrangement, but a life tenant is more often treated as the party liable
- Mobility: a right to reside tied to one specific property can trap an ageing occupant who needs to downsize; a life interest can be drafted as portable
Pro Tip: If the intended occupant might need to move into care or downsize later, ask your solicitor about a portable life estate clause, which lets the interest transfer to a replacement property instead of forcing the occupant to stay put or lose the benefit entirely.
Practical guidance from SV Partners on life interests in property frames this as a straight trade-off: control and capital preservation versus flexibility and financial security for the occupant. There is no universally correct answer, only the one that matches what the testator actually wants to achieve.
Drafting language that avoids a family provision claim
Vague wording is the single biggest cause of later disputes. A clause that simply says a partner may “stay” in the family home leaves a court guessing whether that was meant as a life estate or a bare licence, and courts read ambiguous terms against the whole document rather than any one sentence.
- Use precise legal terms: “occupy and use” for a right to reside, “life estate” or “life tenancy” for a proprietary interest
- If portability matters, state it expressly with rules for replacing the property
- Specify who pays outgoings, or set aside a dedicated fund so the executor isn’t stuck funding rates from estate capital
- Name terminating events clearly (remarriage, repartnering, moving to aged care) and the consequences if they occur
The Law Society Journal’s analysis of life estates and personal rights of residence makes the point plainly: ambiguous wording routinely ends up in litigation. Homemade will clauses are where this risk concentrates, which is exactly why a solicitor review before signing matters more here than almost anywhere else in a will.
Tax and Centrelink effects you can’t ignore
Land tax rules vary by state, and a life tenant can be treated as the effective owner for land tax purposes if the property isn’t their principal residence, which shifts real cost onto the remainder beneficiaries who ultimately inherit it. The Mondaq guidance flags this as a common oversight in home-drafted wills.
- Rental income earned by a life tenant has ordinary income tax consequences, and the ATO’s technical guidance on life estates is the starting point for how that’s assessed
- Occupation or new income streams can shift pension entitlements under Centrelink’s social security means-testing rules
- Get state-specific land tax advice before finalising either clause, since exemptions differ between jurisdictions
Land tax exposure is state-based, not federal — always confirm the current threshold and exemption rules in the relevant state before drafting the clause, since assuming a principal-residence exemption applies can leave beneficiaries with an unexpected bill.
Ending the interest and handling disputes
When a life tenant dies or a right to reside terminates, the property reverts to the remaindermen and the executor has specific duties to formalise that transfer.
- Confirm the terminating event (death, vacating, remarriage, or another named trigger) with proper evidence
- Arrange valuation and transfer of title to the remainder beneficiaries
- Settle any outstanding rates, insurance, or land tax owed by the estate or the former occupant
- Watch for creditor or bankruptcy claims against a life tenant’s interest, which AFSA’s guidance on property in bankruptcy addresses directly
- Where the will’s wording is contested, expect the matter to proceed as a construction dispute or a family provision claim in the NSW Supreme Court
Disputes over these clauses are common enough that early specialist estate litigation advice often heads off a full court fight.
How to decide which option suits your estate plan
- Clarify the real priority: does the surviving partner need housing security, or does preserving capital for children matter more?
- Work through the practical questions: who pays rates and insurance, does the occupant need mobility, and how exposed is the interest to creditors?
- Bring title documents, a current valuation, and beneficiary financial details to your first meeting
- Ask whether a testamentary trust or an outright gift paired with a lifetime licence might solve the problem more cleanly than either standard option
Blended families often find a tailored estate planning structure resolves this better than a one-size-fits-all clause.
A practitioner’s view from Simons George Legal
Blended-family estates are where this choice matters most. Second spouses need housing certainty; adult children from a first marriage want the family home’s value protected. The disputes I see almost always trace back to one vague sentence in a homemade will, not a genuine disagreement over what the testator wanted. Resolving who funds outgoings inside the will itself, rather than leaving it to an executor’s discretion later, removes most of the friction before it starts. If you’re weighing this decision, Simons George Legal offers a complimentary first consultation to talk through your specific family situation.
— George
Funding Your Legal Matter — No Win, No Fee
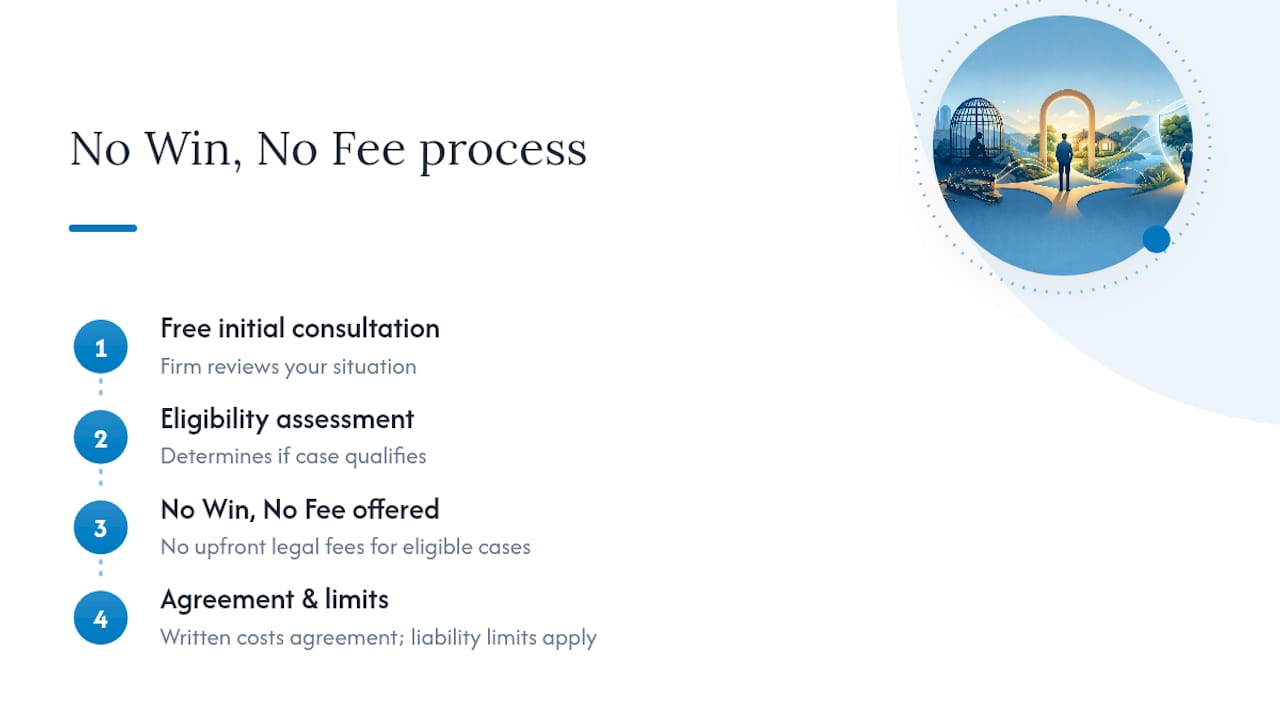
If a life interest or right to reside clause has already caused a dispute in your family, the cost of pursuing your rights shouldn’t be what stops you. Simons George Legal offers No Win, No Fee arrangements for eligible cases, so you can pursue a legitimate claim without paying legal fees upfront. Eligibility is assessed during a free initial consultation, where the firm reviews your situation and gives you a clear picture of your options before anything is signed. This removes the biggest barrier stopping people with genuine claims from getting proper advice. If you believe a will’s wording has disadvantaged you or a family member, book a free case assessment and find out where you stand.
No Win, No Fee arrangements are subject to case eligibility and a written costs agreement. Liability limited by a scheme approved under Professional Standards Legislation.
This article is general information, not a substitute for advice from a qualified lawyer. Consult a qualified legal professional about your own circumstances before acting on anything here.
Sources
- Life estates and personal rights of residence – Law Society Journal
- Right to reside and life estate: what do they mean in your will? – Mondaq
- Life interests in property – SV Partners
- ATO technical direction (TD 2026/D1) – ATO
FAQ
What are the key differences between a right to reside and a life interest?
A life interest is a proprietary estate that can be registered on title and may allow renting or mortgaging; a right to reside is a personal licence allowing occupation only, with no proprietary rights.
What are the disadvantages of a life interest will?
A life interest can expose the property to the life tenant’s creditors, may trigger land tax liability if it isn’t the tenant’s principal residence, and can complicate the estate if the tenant wants to downsize without a portability clause.
What does life interest mean on a property?
It means a named person has the legal right to occupy, and often derive income from, a property for their lifetime or until a specified event, after which ownership reverts to the remainder beneficiaries.
Can a will override the right of survivorship?
A will only controls property the deceased owned in their own name; jointly held property with a right of survivorship generally passes automatically to the surviving joint owner outside the will, so a life interest or right to reside clause has no effect on it. If you’re unsure how your property is held, Simons George Legal can review your title and ownership structure before you finalise your will.